In short
- The ESRS have no independent scope. They are the content of the CSRD duty, so the test is the CSRD test.
- The version in force is Delegated Regulation (EU) 2023/2772 as amended by (EU) 2025/1416. The simplified version was still in scrutiny in August 2026.
- If a customer asks you to report to the ESRS and you are not in scope, you are not obliged to, and if you have no more than an average of 1,000 employees you may decline requests that go beyond the voluntary standard.
The European Sustainability Reporting Standards do not have a scope of their own. They are the content of a duty set elsewhere, so the question of whether they apply to you is the CSRD question: do you exceed both EUR 450 million of net turnover and an average of 1,000 employees, for a financial year beginning on or after 1 January 2027? If yes, the ESRS are what you report to. If no, no version of the ESRS binds you, whatever a customer questionnaire implies. The second half of the question is which version, and on that the answer is the 2023 one, not the simplified one everybody is writing about.
What are the ESRS, in relation to what?
They are a delegated act sitting underneath a directive, which is why they are hard to place.
The reporting duty lives in Articles 19a and 29a of the Accounting Directive, 2013/34/EU, as written there by CSRD. Article 29b is the empowerment that tells the Commission to adopt reporting standards. The Commission did so as Delegated Regulation (EU) 2023/2772, whose Annex I contains ESRS 1, ESRS 2 and the topical standards including ESRS E1 for climate.
So the chain is: directive creates the duty, national law transposes it, delegated act says what the report contains. The ESRS never reach a company that the directive did not reach first. Nothing in Delegated Regulation (EU) 2023/2772 extends the population of reporters.
So who is actually bound to use them?
Whoever is caught by Articles 19a or 29a, on the test set by Directive (EU) 2026/470 of 24 February 2026: net turnover exceeding EUR 450 000 000 and an average of 1 000 employees during the financial year, both, measured on a consolidated basis for a parent undertaking. From financial years beginning on or after 1 January 2027, with national transposition due 19 March 2027.
Plus one separate route: third-country undertakings under Article 40a, where the group has net turnover in the Union above EUR 450 000 000 in each of the last two consecutive financial years and the publishing EU subsidiary or branch exceeds EUR 200 000 000, for financial years starting on or after 1 January 2028.
That is the whole bound population. Two groups who often think they are in are not: listed SMEs, whose wave was deleted outright along with the empowerment for their own standard, and companies caught only by the old large undertaking test, which stopped being the CSRD trigger in February 2026.
Which document applies to you, then?
Depends which of four situations you are in, and the answer differs more than people expect.
| Your situation | What binds you | What to aim at |
|---|---|---|
| Above both thresholds | Full ESRS, Delegated Regulation (EU) 2023/2772 as amended | The version in force, not the simplified one |
| Third-country group above Article 40a thresholds | Article 40a regime, from financial year 2028 | Same standards, later start |
| Below either threshold, asked by a customer | Nothing legally | The voluntary SME standard |
| Below either threshold, reporting by choice | Nothing legally | The voluntary SME standard |
For the bottom two rows the target is the voluntary standard rather than the full ESRS, and the distinction is not cosmetic. Reporting to the full ESRS voluntarily is a very large undertaking that almost nobody below the threshold needs. The VSME standard is what was designed for that population.
Which version of the ESRS is in force?
Delegated Regulation (EU) 2023/2772 of 31 July 2023, as amended by Delegated Regulation (EU) 2025/1416 of 11 July 2025. That is the answer as at 28 August 2026, and it is not the answer most current articles give.
The Commission adopted C(2026) 5010, amending 2023/2772 to simplify the standards, on 3 July 2026. It was still in the Parliament and Council scrutiny period on 28 August 2026 and was not in force. Its own text still carried an unfilled entry-into-force placeholder. The Commission's level two page describes it as not in force until published in the Official Journal.
The practical instruction is simple and it saves rework: design your data collection to the standards in force. If the simplified version reduces what you must disclose, a collection process built for the current version still satisfies it. The reverse is not true.
The one amendment that is in force is worth knowing if you are near the band. Delegated Regulation (EU) 2025/1416 replaced Appendix C of ESRS 1 so that undertakings and groups not exceeding an average of 750 employees may omit the scope 3 and total greenhouse gas datapoints for the first year of preparing a sustainability statement. One year, that band only, and it applies with respect to financial years beginning on or after 1 January 2025.
If you are in scope, which parts of the ESRS actually apply?
Not all of them automatically. The topical standards run through a materiality assessment, and that assessment is a disclosure in itself.
Climate is the exception in practice. ESRS 1 paragraph 32 says that if you conclude climate change is not material and omit all of ESRS E1, you must disclose a detailed explanation of your materiality conclusions on climate, including a forward-looking analysis of the conditions that could lead you to conclude it is material in the future. For any other topic a brief explanation suffices. So E1 is droppable in theory and expensive to drop in practice.
Which is why the greenhouse gas work starts first for almost every in-scope company. Disclosure Requirement E1-6 asks for gross scope 1, gross scope 2 on both location based and market based bases, gross scope 3 for each significant category, a total on both scope 2 bases, and intensity per net revenue reconciled to the financial statements. The boundary is your financial consolidation scope, then operationally controlled entities at 100 percent for emissions.
You are not in scope but a customer says you must use the ESRS. Now what?
They are wrong about the obligation, and how you say so matters commercially.
Your customer has a duty to report value chain information and the standards tell them to estimate with sector averages where they cannot collect. Asking you is easier than estimating, so they ask. Nothing in EU law converts that into an obligation on you.
Since February 2026 there is also a ceiling with legal force. If you do not exceed an average of 1,000 employees and you sit in a reporter's value chain, you are a protected undertaking. You may decline to provide information exceeding the voluntary standards where the request is made for the purpose of CSRD reporting, a contractual provision to the contrary is not binding, and the reporter must tell you which parts of the request exceed the standard.
The cap has edges. It applies only to CSRD reporting requests, so due diligence, risk management, tenders and ordinary procurement questions are outside it, and it does not stop voluntary sharing. Using it well means answering everything inside the ceiling promptly and declining above it in writing. That conversation is what a customer may not ask you.
What is the first practical step either way?
An inventory, at different depths.
If you are bound by the ESRS, start with the boundary and the scope 2 pair, because those two decisions determine every collection request you send and both are slow to unwind. If you are not, build a repeatable scope 1 and 2 inventory you can reuse across every customer who asks, and keep the method stable so year two compares with year one.
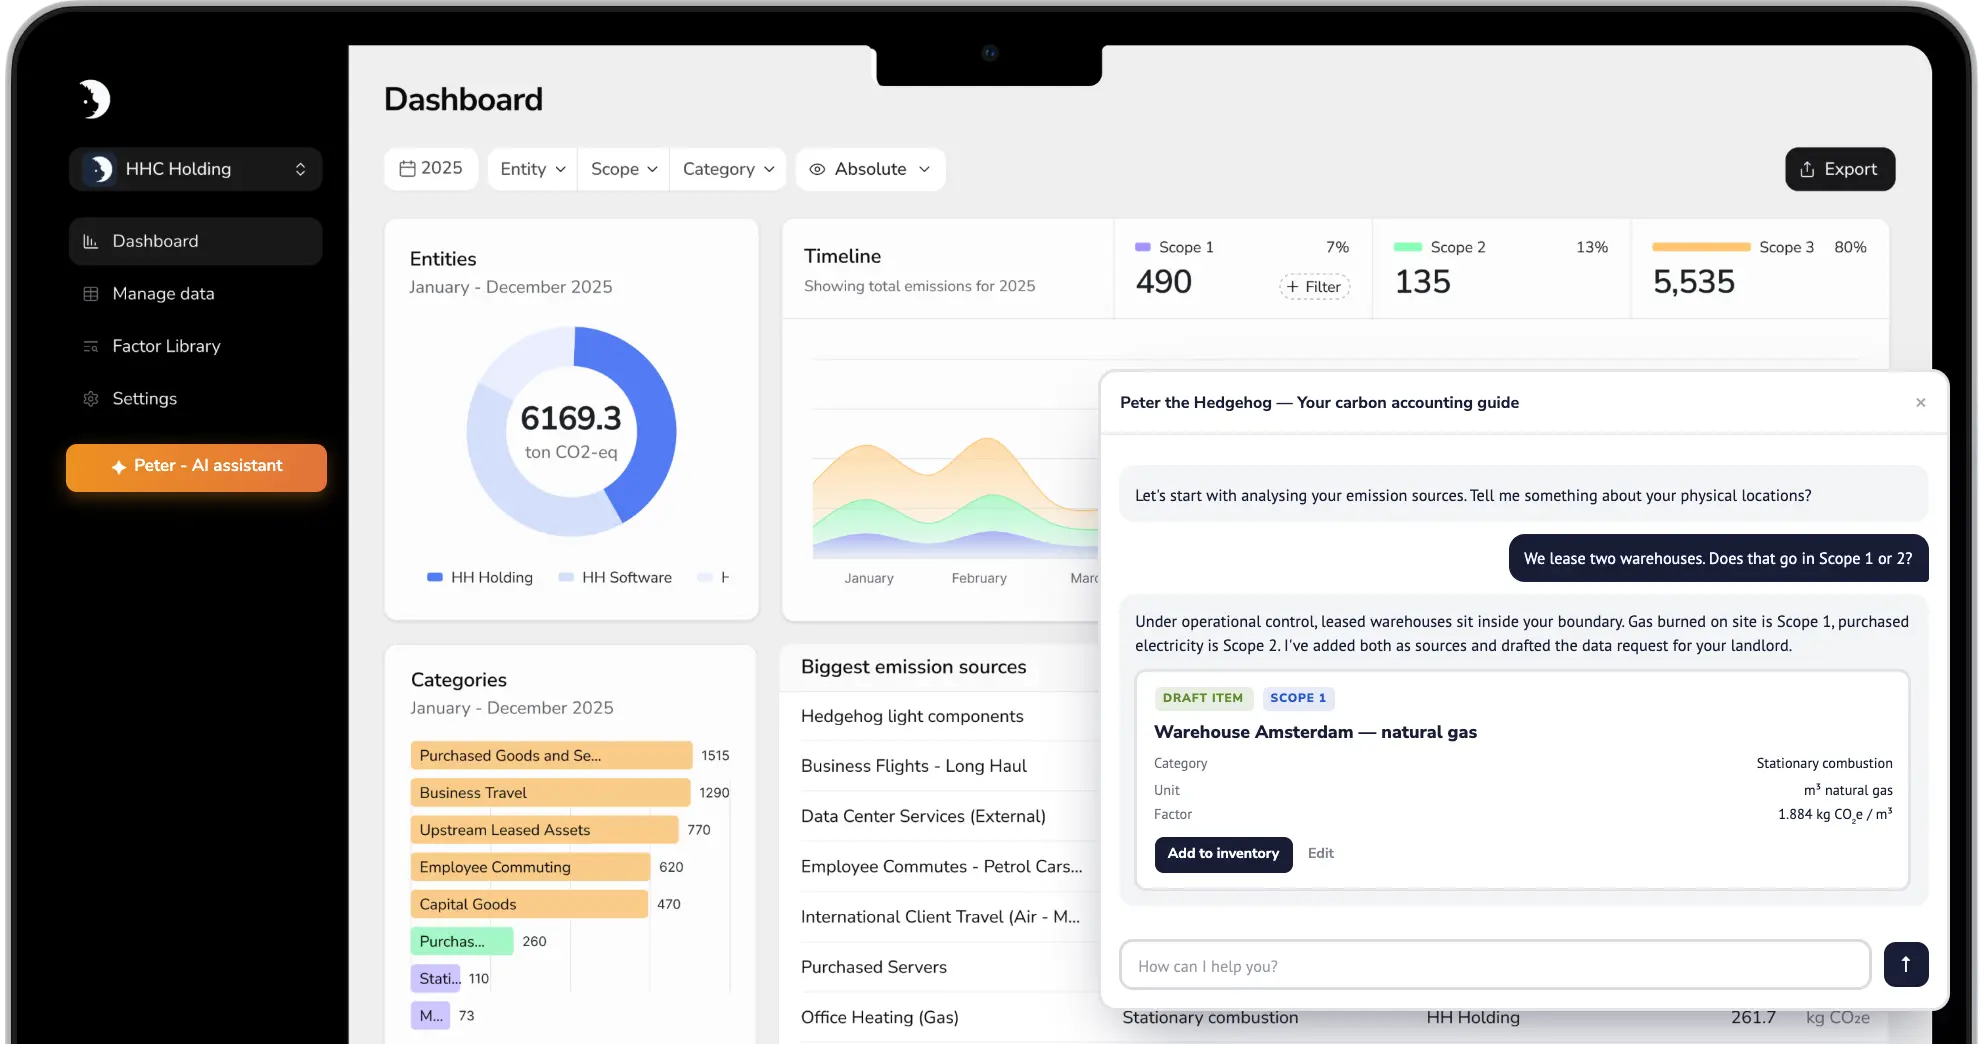
The platform does the emissions half on either side of the line, with over 20,000 spend based and activity based factors, entity management across locations and sites, and 5,000+ users. A free account produces a first number without a sales call. If you want a person alongside it, carbon footprint consulting is the route.
One honest limit before you start. A Small Business reviewer rated us 5 out of 5 on G2 in August 2026 and said that loading data is manual and takes effort, adding that once loaded it works well. The first load is the cost, and it is a real one.
Sources: Delegated Regulation (EU) 2023/2772 of 31 July 2023, Delegated Regulation (EU) 2025/1416 of 11 July 2025, Directive 2013/34/EU Articles 19a, 29a, 29b and 40a as amended by Directive (EU) 2026/470, Commission act C(2026) 5010 of 3 July 2026. Read against the Official Journal text and verified 28 August 2026.
Facts on this page were last verified on 2026-09-17.