
In short
- The deliverable is an audited organisational greenhouse gas inventory in CO2 equivalents, not a product footprint and not a policy document.
- Trede 1 needs scope 1 and 2 plus non-CO2 greenhouse gases. Trede 2 adds quantified scope 3, a klimaattransitieplan and a qualitative look at emissions outside the scopes.
- Under Handboek 4.0 the base year at an initial audit may be no more than three years before the year of that audit.
The CO2-Prestatieladder asks for one thing: an audited organisational greenhouse gas inventory, in CO2 equivalents, that a certifying body can follow back to source. Everything else on the requirement list is built on it. Which trede, meaning rung, you certify against decides how far that inventory reaches: your own operations at trede 1, the value chain at trede 2, everything you can influence plus a quantified route to zero at trede 3. The scheme also constrains which year the numbers may come from, which is the requirement most often discovered late.
What does each trede add to the data set?
| Data item | Trede 1 | Trede 2 | Trede 3 |
|---|---|---|---|
| Scope 1 and scope 2 emissions | Mapped | Mapped | Mapped |
| Non-CO2 greenhouse gases | Mandatory to report | Mandatory | Mandatory |
| Energy use and its reduction | Required | Required | Required |
| Named key roles for CO2 management | Required | Required | Required |
| Reduction goals | Short term, one to three years | Medium term strategy, five to ten years | Route to zero by 2050 at the latest |
| Scope 3 emissions | Not required | Quantitatively mandatory | Quantitatively mandatory |
| Klimaattransitieplan (climate transition plan) | Not required | For core activities | For all activities, quantified to zero in scope 1, 2 and 3 |
| Emissions outside the standard scopes (OBE) | Not required | Investigated qualitatively | Quantitative insight |
| Participation in an initiative or collaboration | Know which partners you could work with | Active participation | A leading role |
| External expert dialogue on the plan | Not required | Not required | Dialogue with independent external experts |
SKAO puts trede 1 at roughly the effort of niveau 3 under the old Handboek 3.1, and trede 2 at roughly the effort of niveau 5. Trede 3 has no equivalent in 3.1 at all, so there is no prior workload to calibrate against.
Why is non-CO2 reporting the change that catches people?
Because it turns a CO2 inventory into a CO2-equivalent one from the first rung upward.
Under Handboek 3.1 reporting on greenhouse gases other than CO2 was optional. Under Handboek 4.0 it is mandatory at trede 1. In practice that means the inventory boundary is not just the emissions you were already counting converted into a different unit; there are sources you may never have collected data on at all, and the collection has to start somewhere in the organisation that has never been asked for it before.
Related and often overlooked: Harmonisatiebesluit 1 of 23 October 2025 covers business travel targets and Well-to-Tank emissions at trede 1. Harmonisatiebesluiten are binding from publication rather than at the next handbook release, so a requirement list assembled from the handbook text alone is already incomplete. There were three of them when we last checked SKAO's documents page, on 24 September 2026.
What does quantitatively mandatory scope 3 mean at trede 2?
It means numbers, not a narrative, and it is the item that decides whether trede 2 is realistic this year.
Under Handboek 3.1 the scope 3 obligation arrived at niveau 4 as a reporting duty. At trede 2 of 4.0 it is quantitative, which converts it from a documentation exercise into a supply chain data exercise. The distinction matters because of calendar time rather than difficulty: the data sits with suppliers who have no obligation to answer you, on their timetable rather than yours, and the number of rounds you need to get usable answers is not something you can compress in the last month before an audit.
The klimaattransitieplan sits on top of that. At trede 2 it covers your core activities over a five to ten year horizon; at trede 3 it covers all activities with a quantified route to zero emissions in scope 1, 2 and 3 by 2050 at the latest. A plan is only as good as the inventory underneath it, so the scope 3 quantification is the gating item for both. This is scope 3 consulting work in most organisations rather than something the bid team can absorb.
What is OBE and what evidence does it need?
OBE stands for overige beinvloedbare emissies, other influenceable emissions: emissions that fall outside scope 1, 2 and 3 but which the organisation can still influence. It is new in Handboek 4.0 and has no counterpart in 3.1.
The evidence bar changes with the trede. At trede 2 the requirement is a qualitative investigation, so the deliverable is a reasoned account of what you can influence and how. At trede 3 the requirement is quantitative insight, which means the same subject with numbers behind it. Budget for the gap: moving from trede 2 to trede 3 is not a matter of restating the trede 2 work more formally.
Which year do the numbers have to come from?
This is the requirement that quietly invalidates preparation done too early.
Under Handboek 4.0, section 9.1.4, the base year at the initial audit may not be more than three years before the year of that audit. Earlier handbooks left organisations largely free to pick a base year. The rule was introduced to make certificate holders comparable with one another and to align the scheme with the CSRD, which is one of the four changes SKAO names in 4.0.
Harmonisatiebesluit 3 of 1 June 2026 relaxes it in one direction only: a less recent base year is allowed where legal requirements demand it. That is a narrow exception, not a general escape.
The planning consequence is simple and easy to miss. If you build a careful baseline now and then take an initial audit three or four years later, the baseline is out of the window on the day you need it. Fix the audit date first and choose the base year against it, not the other way around.
What does the auditor actually check?
Traceability, and increasingly in SKAO's own systems rather than yours.
Evidence under 4.0 is assembled in SKAO's online environment, Mijn CO2-Prestatieladder, rather than compiled into a folder for audit day. A certifying body follows a figure back to where it came from, so the working standard is not that the total is defensible but that each input is. That is a different requirement from most voluntary reporting, where a plausible total is usually the end of the conversation.
There is also a clock on findings now. Harmonisatiebesluit 2 of 11 December 2025 requires a corrective action plan within three months of a minor non-conformity, replacing the handbook's original rule of by the next annual audit. A finding you would once have folded into the following cycle is a three month deliverable.
What does this mean for the systems you keep it in?
The combination of an annual audited inventory, a base year rule, a klimaattransitieplan and a certifying body who traces figures back to source is what makes this a system problem rather than a spreadsheet problem. Spreadsheets fail the traceability test first, usually at the point where somebody asks which factor was applied to a line and when it changed.
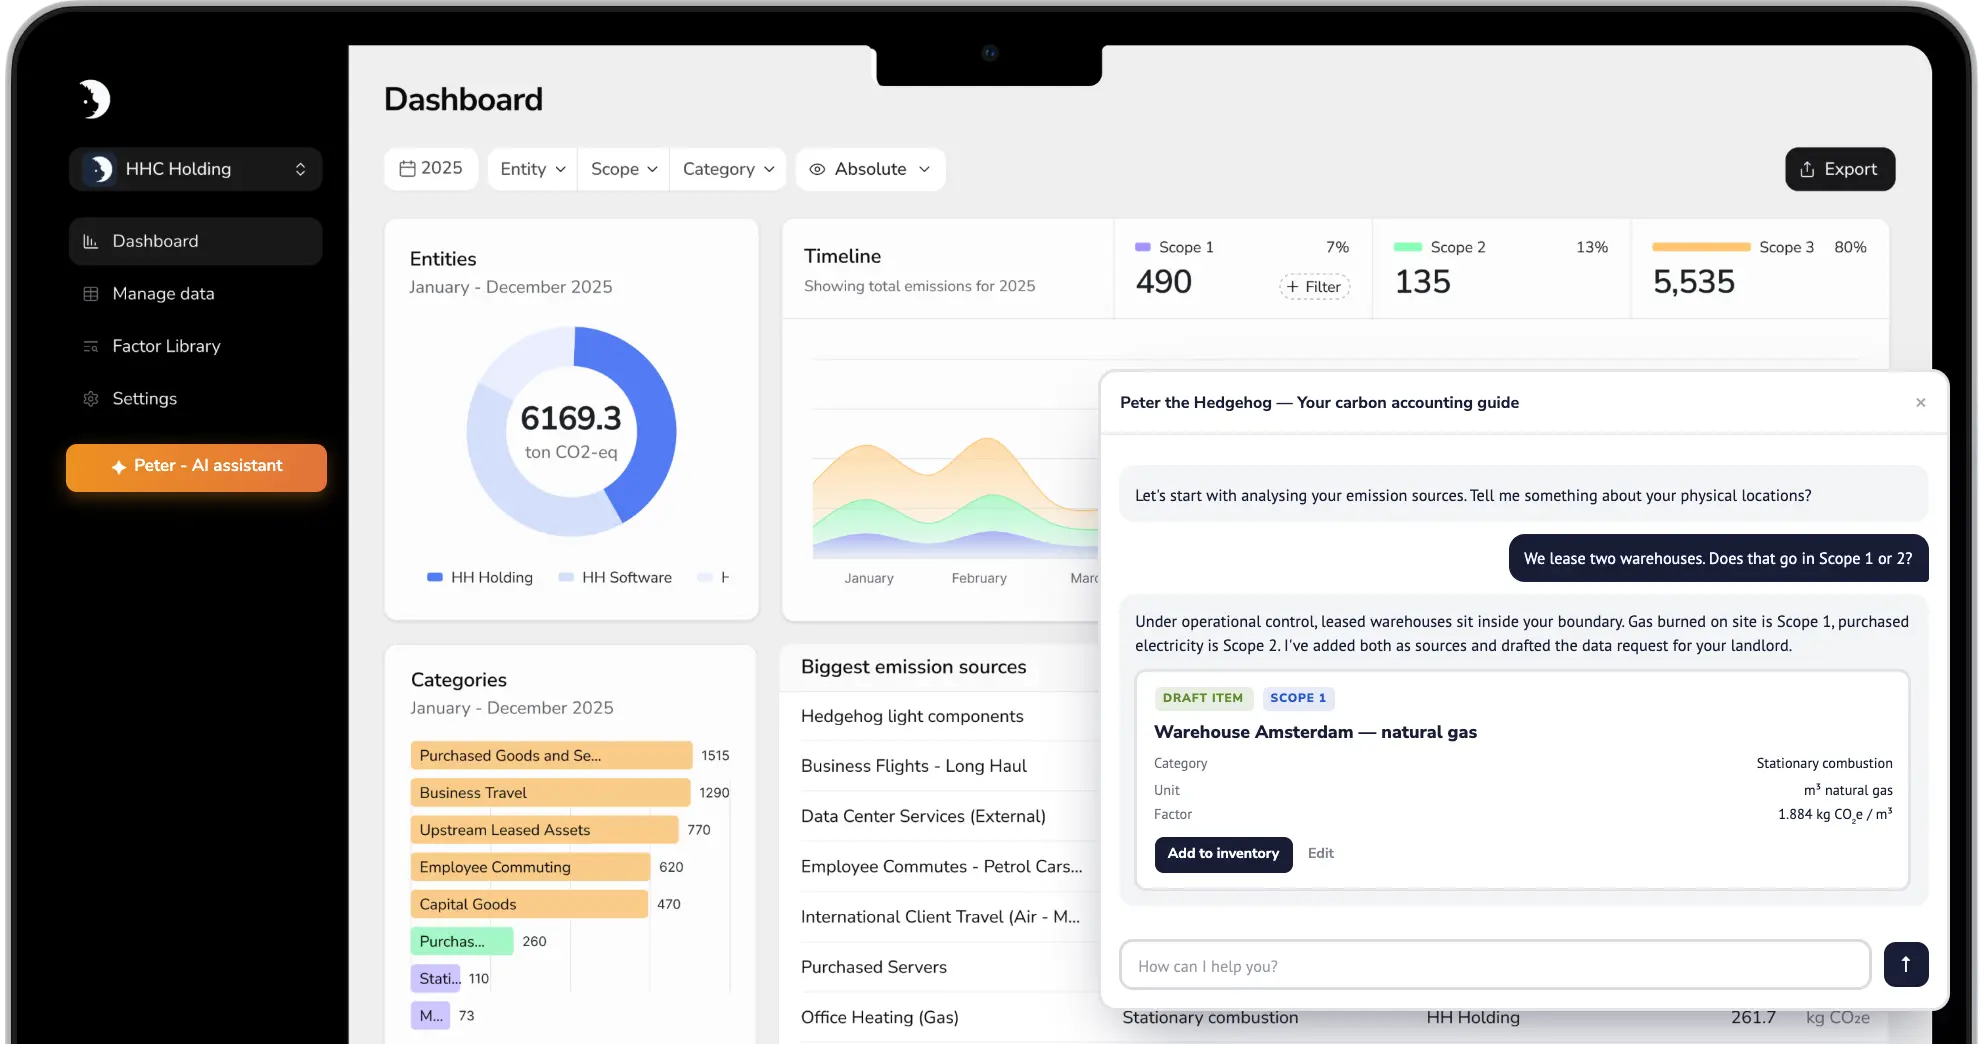
The Hedgehog platform names the CO2-Prestatieladder among its reporting outputs, carries over 20,000 spend-based and activity-based factors that you can supplement with your own organisation-specific or supplier-specific data, and reports 5,000+ users on its platform page. The limitation to test on your own data before an audit rather than during one: a mid-market reviewer on G2 in July 2026 rated it 4 out of 5 and said the applied conversion factors and distance calculations are not shown to the user, so tracing how a given input became a given entry is not always possible from the interface. On a scheme built around exactly that question, run a trace on your own worst data set early.
If the base year decision or the trede choice is what is actually blocking you, that is carbon footprint consulting rather than a tooling question. If you are selecting a tool for the first time, our guide to choosing the right carbon accounting software sets out what to ask, and our introduction to the CO2-Prestatieladder for SMEs covers the scheme.
Sources: SKAO Handboek 4.0 documents and migration guidance, Overgangsregeling 3.1-4.0 v1.1 of 1 July 2025, Handboek 3.1, Harmonisatiebesluiten 1 to 3, Hedgehog platform, Hedgehog on G2. Verified 28 August 2026.
Facts on this page were last verified on 2026-09-24.